Connected television captures roughly a fifth of the time people spend with media in the United States, yet only about 7.7 percent of ad spend, according to eMarketer. That gap is the most useful number in advertising right now, because it explains why so much premium video is being commissioned and where it is being made.
The same forecaster expects US connected TV ad spend to reach about 37.95 billion USD in 2026, up 14.5 percent year on year. For the first time, the US connected TV upfront (17.73 billion USD) is larger than the primetime linear upfront (16.98 billion USD). The screen in the living room is now sold like broadcast, and buyers expect it to look like broadcast. Demand for connected TV video production in Vietnam follows from that expectation.
The catch up trade
A market that holds a fifth of attention and under a tenth of spend is not in equilibrium. Analysts at eMarketer and Dentsu describe the result as several years of double digit catch up growth. Dentsu’s 2026 forecast puts global online video advertising up 11.5 percent, roughly twice the pace of the total ad market, in a year when total global spend passes 1 trillion USD on its measure. WARC, using a wider methodology, puts the 2026 total nearer 1.30 trillion USD.
Growth concentrated in one format changes what production companies are asked to deliver. A spot bought for a large screen, in a lean back setting, is judged against film and premium television rather than against a social clip. The bar moves from adequate to finished.
Southeast Asia is not a footnote
The region is where the catch up story looks steepest. Industry reporting on programmatic buying in Southeast Asia points to open connected TV spend rising around 43 percent in the first quarter of 2025 against 2023, and surveys of Asia Pacific marketers describe a majority shifting a large share of budgets toward connected inventory. Treat the exact percentages as indicative, since they come from vendor and trade sources rather than a single audited series. The direction is not in dispute.
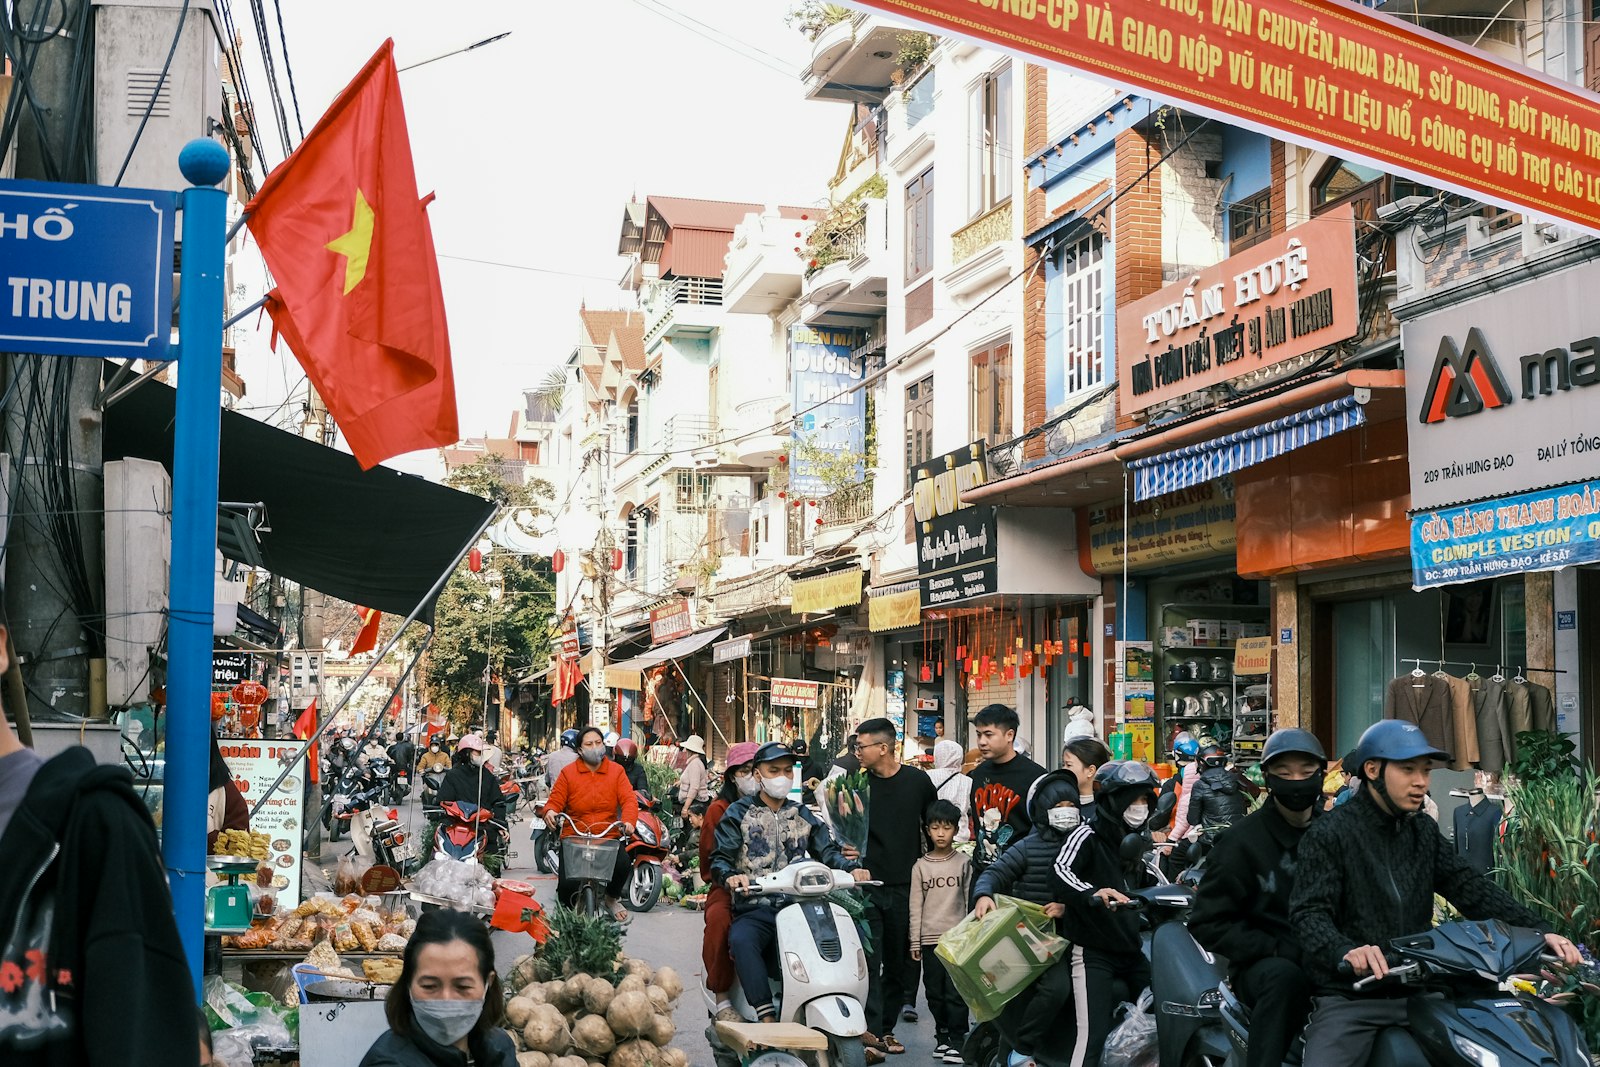
The wider backdrop supports it. Google, Temasek and Bain’s SEA economy report estimates the regional digital economy above 300 billion USD in 2025, with online media advertising growing 16 percent. In Vietnam, We Are Social and Meltwater count 79.8 million internet users and smartphone penetration of 84.4 percent against a global average near 63 percent. Vietnam is a video first market with a young, screen fluent audience, and advertisers who need reach there are buying premium video inventory in growing volume.
What the buyer now asks for
Media planners buying connected inventory increasingly ask for a single hero film that survives scrutiny on a 65 inch screen, then cut down for social and retail placements. That reverses the older logic, in which a vertical clip was the base unit and the premium film an occasional luxury. The consequence for regional production is a shift toward narrative driven commercials and brand films with a clear finished standard, made in fewer, larger units.
For international agencies, the practical question becomes cost against finish. Thailand has raised its production rebate to as much as 30 percent, and Malaysia’s programme reaches 30 to 35 percent with a cultural uplift, as documented by their national film offices and trade reporting. Vietnam offers no comparable rebate, and competes instead on total cost, a deep local crew pool and a domestic audience that is itself among the world’s heaviest video users.
Where Saigon fits
Ho Chi Minh City has drawn a growing base of multinational and regional brands, with registered foreign direct investment in the city reaching 8.37 billion USD in 2025, according to municipal figures reported by Xinhua and VietnamPlus. Vietnam’s own national strategy for cultural industries, set out in Decision 2486 in late 2025, names film and advertising among priority sectors.
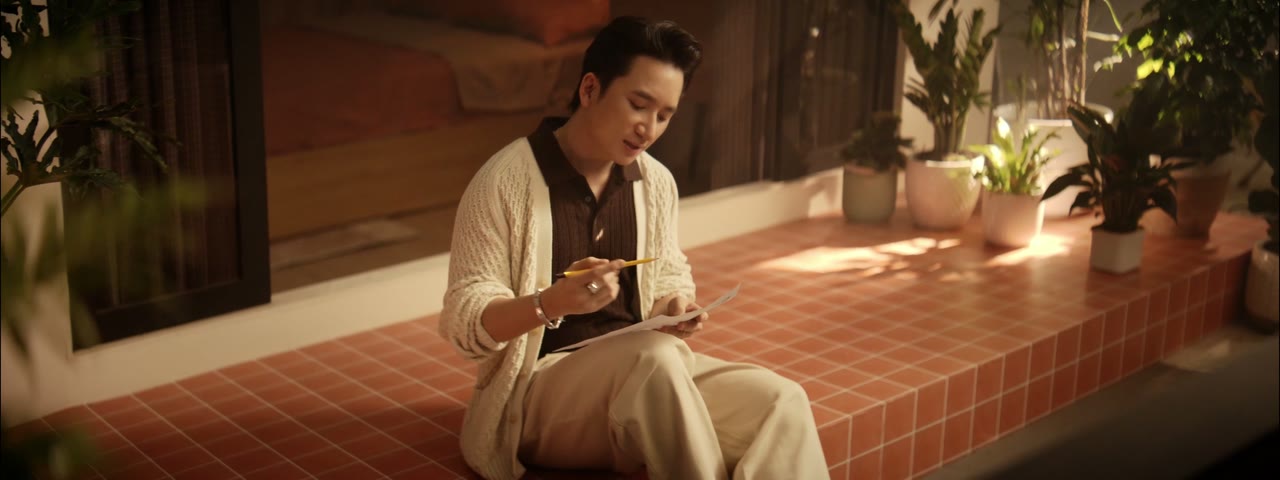
Within that landscape, a production house in Saigon that shoots and finishes under one roof, such as Hoang Films, sits on the supply side of the connected TV trade: a small, local operator working to a premium finish. The studio has operated in Ho Chi Minh City for around three years, with more than fifty projects behind it, a scale that reflects how much of the market is served by compact teams rather than large facilities. Its filmography, at /#work, gives a sense of the commercial and brand work that now fills this slot, and the home page sets out the wider service line.
The honest limits
The picture has caveats. Vietnam’s connected TV ad market is small against the United States or China, and audited local spend data is thin. eMarketer’s country level figures for 2026 list the US at around 36.95 billion USD, the United Kingdom at 3.45 billion and China at 3.40 billion, with Southeast Asia far behind. Infrastructure for very large shoots is thinner than in Bangkok. Fees quoted by vendors for offshore savings, often 50 to 70 percent against Western in house teams, are indicative and should be read as such.
Still, the direction of travel is measurable. Attention has moved to the big screen, spend is following with a lag, and the region with the fastest growing audience needs films that hold up at that size. The production side of the market is being built accordingly, one finished commercial at a time.